

Prosecution Eyes Turnover Of VP Sara Duterte’s Tax Cases To BIR
“On our part, we are focused on the impeachment trial. The prosecution panel is willing to share with BIR (Bureau of Internal Revenue) the documents that we already have, because this is public record,” House prosecutor Zia Alonto Adiong said.
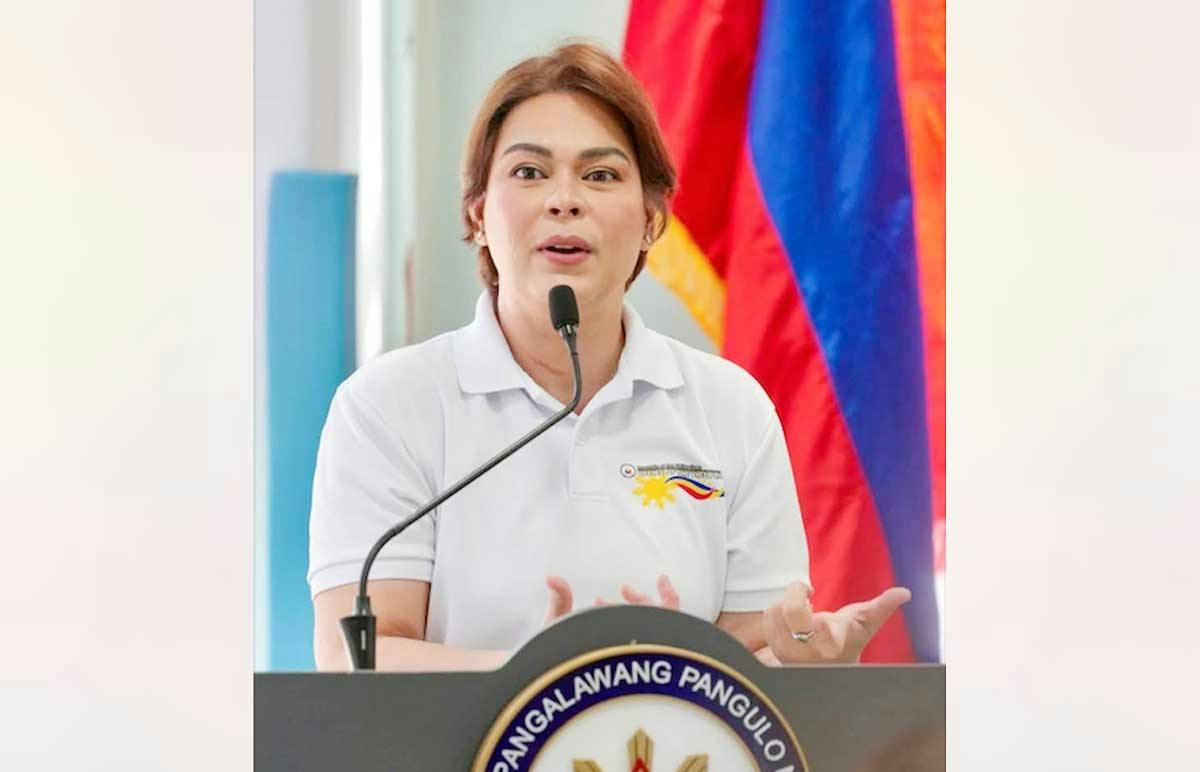
The House prosecution panel plans to turn over tax documents of Vice President Sara Duterte and companies linked to her husband Manases Carpio to the Bureau of Internal Revenue (BIR), for the possible filing of tax evasion charges.
“As far as I know, the BIR has already issued a letter of authority,” House prosecutor and Lanao del Sur 1st district Rep. Zia Alonto Adiong said on Sunday, Nov. 1.
“On our part, we are focused on the impeachment trial. The prosecution panel is willing to share with BIR the documents that we already have, because this is public record,” he noted.
There are two possible tax evasion cases against the Duterte couple – the P111.8-million gap in the VP’s declared income against her alleged conjugal unexplained wealth, and the tax violations of Carpio-linked firms Metro City Chow Inc., Cale88 Foods Corp. and GenCorp.
Adiong used as basis financial records showing the Vice President and Carpio’s P174.96-million bank inflows compared to P63.11 million in declared income from 2022 to 2025, leaving a difference of P111.85 million.
The figures were part of the findings of forensic analyst Alexander Cabrera, who examined Duterte’s income tax returns, bank records and other financial documents presented during the Senate impeachment trial.
Cabrera included the P111.85-million alleged undeclared income in his broader estimate of P817.87 million in unexplained wealth and undeclared assets involving the Duterte couple, which he predicted could reach at least P1.5 billion from 2022 to 2025.
As for the companies, Adiong said these also involve hundreds of millions of pesos they discovered.
“It’s a difference of hundreds of millions that they declared, those financial statements that were audited, and without the real income, the money inflows, the companies’ revenues and based on their corporate accounts, as against those bank deposits in their standing accounts,” he said.
Under Section 248(B) of the National Internal Revenue Code, failure to report sales, receipts or income in an amount exceeding 30 percent of that declared in a tax return may constitute substantial underdeclaration and prima facie evidence of a false or fraudulent return.
However, the BIR must determine whether the questioned bank inflows represent taxable sales, receipts or income, rather than loans, transfers or other legitimate transactions.
“I’m sure the BIR has all the means to review and to get access to documents that they need, and they need to secure these so that they can see and assess for themselves if there is some probative value on the pieces of evidence that came out during the testimony,” Adiong said.